6.4% or 6.5%: How a 10-Basis-Point Stress Test Shift Changes Your Approval
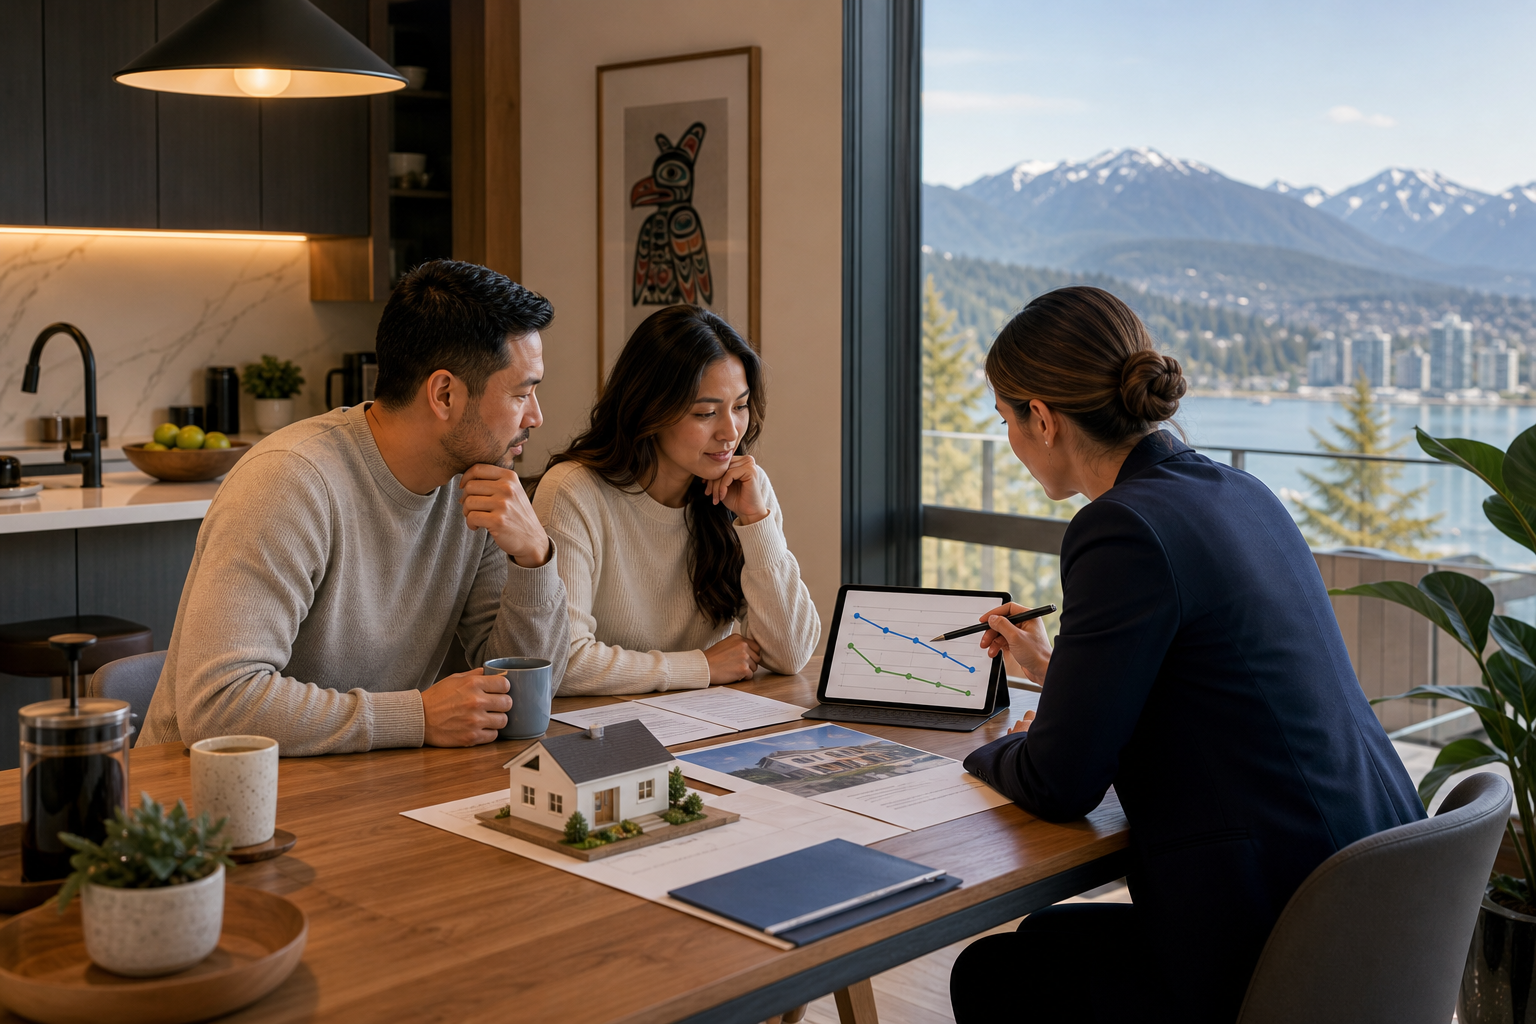
Picture two quotes on your kitchen table, one at 4.4% and one at 4.5%, and a lender who will judge you on neither of them. Under the federal stress test, which is still the rule in October 2026, you qualify at the higher of your contract rate plus 2 percentage points, or 5.25%. So the 4.4% quote is tested at 6.4% and the 4.5% quote at 6.5%.
That one-tenth gap does shrink what you can borrow. For most self-employed buyers it shrinks it by less than they fear. The useful skill is pricing that tenth in dollars, then setting it beside the other moves you can make. Once you see the sizes side by side, you know where to spend your effort before you apply.
Know which hurdle you're up against
The stress test has two parts. When contract rates sit below 3.25%, the 5.25% floor sets your qualifying rate and a small rate difference changes nothing. Above 3.25%, the "plus 2" buffer takes over, and every basis point you pay (a basis point is one-hundredth of a percent) carries straight through to your qualifying rate. At 4.4% or 4.5%, you're in buffer territory.
The same income, two qualifying rates
Here is an illustrative file. You're self-employed, and the two-year average of Line 15000 (total income) on your T1 Generals comes to $100,000. Lenders usually cap housing costs at about 39% of income, which is the gross debt service ratio. That works out to $3,250 a month. Say property tax and heat take $400 of it, leaving $2,850 for mortgage payments. Use a 25-year amortization.
Tested at 6.4%: $2,850 a month supports about $429,400.
Tested at 6.5%: $2,850 a month supports about $425,500.
The difference is roughly $3,900. Turned around, the extra tenth adds about $26 to the monthly payment the lender tests against. Covering that within a 39% ratio takes about $800 more in reported annual income.
Put a bigger lever next to it
If you're putting 20% or more down, a 30-year amortization is usually available. At the same 6.5% qualifying rate and the same $2,850, the longer amortization supports about $455,000. That's around $29,500 more than the 25-year version, roughly seven times what the rate difference moved.
Income presentation can be just as powerful. Lenders often add back non-cash write-offs such as capital cost allowance or a home office deduction before the stress test is run. For insured mortgages, CMHC allows a 15% gross-up of self-employed income and wants 24 consecutive months of financials. Lower taxes this year can mean less borrowing room next year, so the time to plan your income is about two years before you buy.
The friction differs too. Shaving 10 basis points might mean a longer term or a smaller lender. A 30-year amortization means more interest over the life of the loan. Add-backs depend on clean, well-prepared statements. Each lever has a cost, and you can see it before you decide.
Shorter terms bring one more consideration. If you choose a one- to three-year term, you'll face renewal sooner. A straight switch to a new lender at renewal is exempt from the stress test, but any refinance means qualifying again.
The pivot
If your file clears with more than about $4,000 of room, the 6.4% versus 6.5% choice is about what you'll pay each month, and you should pick it on cost and terms. If you're within a few thousand dollars of your limit, that tenth decides the approval, and you should chase it alongside amortization and add-backs.
Your sale price sets which situation you're in, so run your own numbers before you shop rates. I'm happy to work through them with you, using your actual returns, so you can see which lever moves your file the furthest.

Picture two quotes on your kitchen table, one at 4.4% and one at 4.5%, and a lender who will judge you on neither of them. Under the federal stress test, which is still the rule in October 2026, you qualify at the higher of your contract rate plus 2 percentage points, or 5.25%. So the 4.4% quote is tested at 6.4% and the 4.5% quote at 6.5%.
That one-tenth gap does shrink what you can borrow. For most self-employed buyers it shrinks it by less than they fear. The useful skill is pricing that tenth in dollars, then setting it beside the other moves you can make. Once you see the sizes side by side, you know where to spend your effort before you apply.
Know which hurdle you're up against
The stress test has two parts. When contract rates sit below 3.25%, the 5.25% floor sets your qualifying rate and a small rate difference changes nothing. Above 3.25%, the "plus 2" buffer takes over, and every basis point you pay (a basis point is one-hundredth of a percent) carries straight through to your qualifying rate. At 4.4% or 4.5%, you're in buffer territory.
The same income, two qualifying rates
Here is an illustrative file. You're self-employed, and the two-year average of Line 15000 (total income) on your T1 Generals comes to $100,000. Lenders usually cap housing costs at about 39% of income, which is the gross debt service ratio. That works out to $3,250 a month. Say property tax and heat take $400 of it, leaving $2,850 for mortgage payments. Use a 25-year amortization.
The difference is roughly $3,900. Turned around, the extra tenth adds about $26 to the monthly payment the lender tests against. Covering that within a 39% ratio takes about $800 more in reported annual income.
Put a bigger lever next to it
If you're putting 20% or more down, a 30-year amortization is usually available. At the same 6.5% qualifying rate and the same $2,850, the longer amortization supports about $455,000. That's around $29,500 more than the 25-year version, roughly seven times what the rate difference moved.
Income presentation can be just as powerful. Lenders often add back non-cash write-offs such as capital cost allowance or a home office deduction before the stress test is run. For insured mortgages, CMHC allows a 15% gross-up of self-employed income and wants 24 consecutive months of financials. Lower taxes this year can mean less borrowing room next year, so the time to plan your income is about two years before you buy.
The friction differs too. Shaving 10 basis points might mean a longer term or a smaller lender. A 30-year amortization means more interest over the life of the loan. Add-backs depend on clean, well-prepared statements. Each lever has a cost, and you can see it before you decide.
Shorter terms bring one more consideration. If you choose a one- to three-year term, you'll face renewal sooner. A straight switch to a new lender at renewal is exempt from the stress test, but any refinance means qualifying again.
The pivot
If your file clears with more than about $4,000 of room, the 6.4% versus 6.5% choice is about what you'll pay each month, and you should pick it on cost and terms. If you're within a few thousand dollars of your limit, that tenth decides the approval, and you should chase it alongside amortization and add-backs.
Your sale price sets which situation you're in, so run your own numbers before you shop rates. I'm happy to work through them with you, using your actual returns, so you can see which lever moves your file the furthest.
Read Next
Morgan Stanley's Record Quarter Shows How IPO Windfalls Become Lasting Wealth Clients
Buy Now or Wait? How July's $6,600 Price Rise Shifts Your Qualifying Math
Brookfield's US$444 Million Bet on Indian Warehouses Shows Where Big Capital Is Heading
Up to 4.69 Million Homes Needed by 2036: Buy Now or Wait in BC?