The Resource Boom That Won't Help Your Mortgage Application
Resource booms concentrate wealth in specific sectors like mining and energy infrastructure while creating economic headwinds for service-based businesses elsewhere in the country. When commodity prices surge, input costs rise, skilled labor migrates to higher-paying regions, and interest rates remain elevated, leaving service business owners facing margin compression and tighter lending standards despite headlines celebrating economic growth. For mortgage qualification, lenders apply fixed underwriting rules based on documented personal income and debt ratios, not provincial GDP figures, meaning a booming resource sector can paradoxically make it harder for self-employed borrowers to access credit.
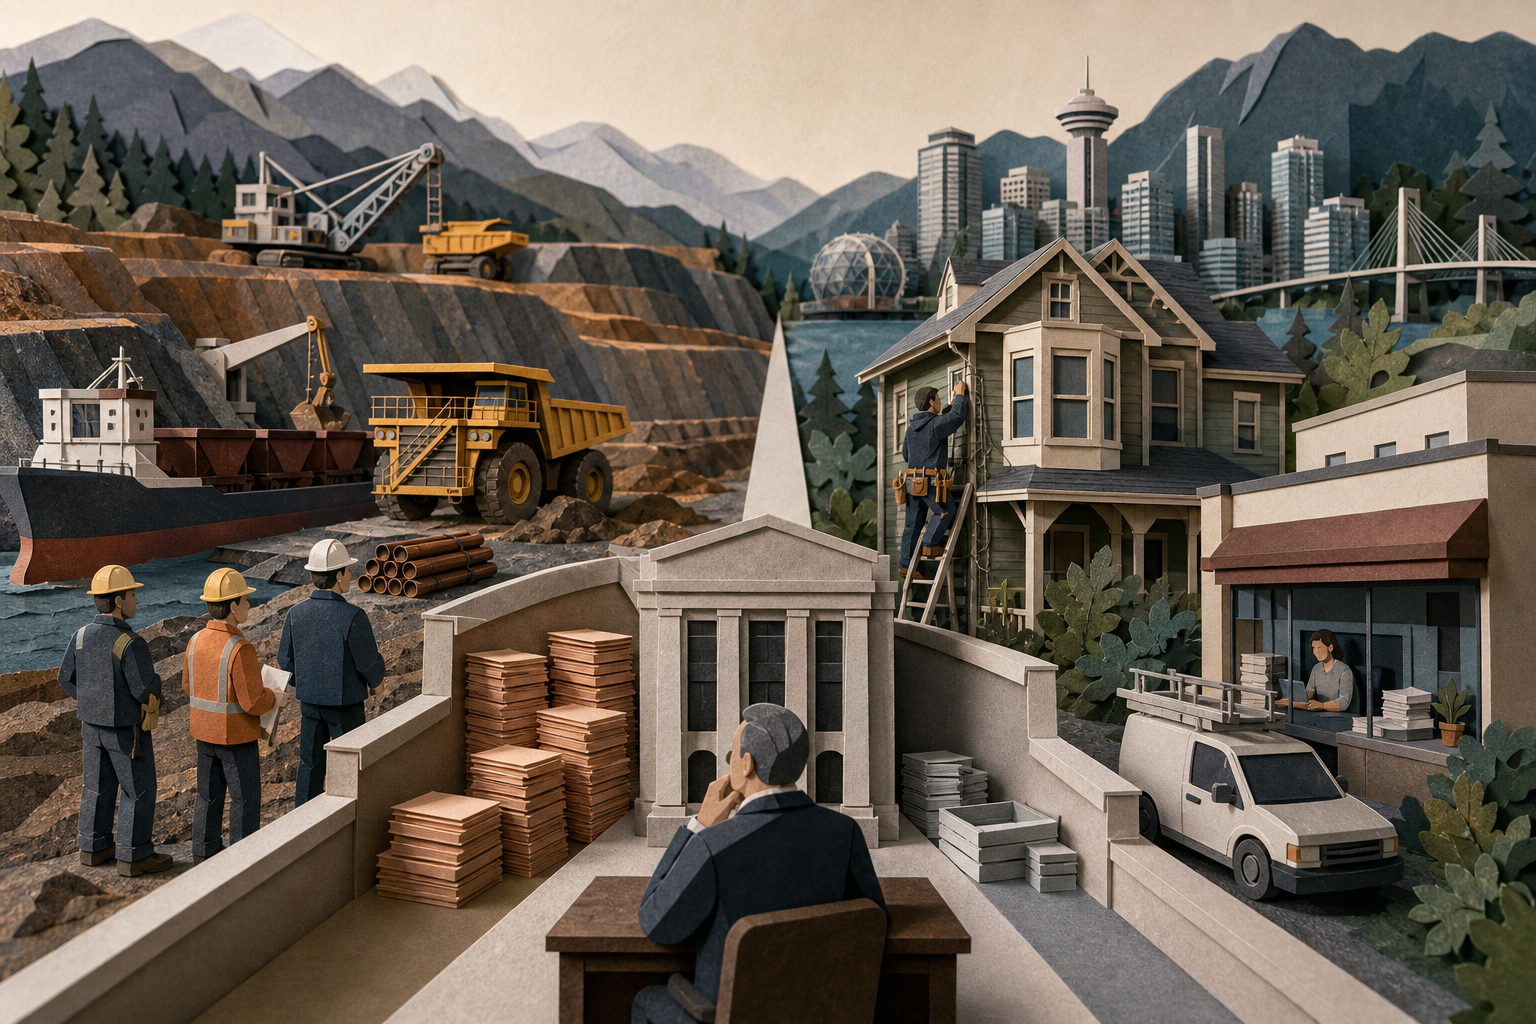
Resource booms concentrate wealth in narrow corridors. The Northeast has laydown yards where LNG equipment sits before shipment. Open-pit mines in the Interior require haul trucks for servicing. The money flows to heavy equipment operators, engineering firms with energy contracts, and suppliers who move bulk materials. It does not flow to the electrician rewiring a heritage home on Vancouver Island or the bookkeeper running a service practice out of a strip mall.
The confusion comes from treating GDP growth as a single lever that lifts all boats. GDP measures the total value of goods and services produced across the country. When copper prices surge and British Columbia's mining output climbs, the provincial balance sheet improves. Tax revenue rises. Employment in resource extraction ticks up. But a mortgage lender does not underwrite your application based on provincial GDP. They underwrite it based on two years of your T1 Generals, your debt service ratios, and whether your business income meets CMHC's requirement for 24 consecutive months of financial statements.
Why lenders tighten during booms
When resource sectors heat up, banks recalibrate their risk appetite. A portfolio heavy in energy and mining loans creates concentration risk. To balance the exposure, institutions often pull back on complex, manual underwriting, the kind required for self-employed borrowers whose income fluctuates or whose write-offs make qualifying income hard to calculate.
At the same time, a strong economy delays interest rate cuts. The Bank of Canada's overnight rate fell from 4.25 percent in early September 2024 to 3.00 percent by January 2025, as inflation made progress toward the 2% target. Strong export numbers and rising commodity prices kept the central bank cautious. For a contractor hoping lower rates would make the mortgage payment manageable, the resource boom became the obstacle, not the opportunity.
The inflation nobody talks about
Resource booms drive up input costs. Diesel climbs. Lumber becomes expensive because mills prioritize high-margin export orders. Skilled labor migrates toward the Peace River region or the Interior, where day rates are higher. A service business in the Comox Valley sees its material and labor costs rise without seeing a corresponding increase in revenue.
The result is margin compression. Your gross revenue might hold steady, but net income, the number lenders actually use, shrinks. When you file your next tax return, the qualifying income drops. The mortgage you could have qualified for a year ago is now out of reach, even though the headlines say the economy is booming.
What lenders actually see
OSFI's B-20 stress test requires that you qualify at the greater of your contract rate plus 100 basis points, or 5.25 percent. That floor does not move when commodity prices rise. CMHC's 15 percent gross-up for self-employed income allows a small deduction to account for business write-offs, and has not changed in years. The Gross Debt Service ratio ceiling is still 39 percent. The Total Debt Service ceiling is still 44 percent.
These are fixed rules. They do not loosen because Canada's resource exports increased. They tighten when your documented income falls or when your debt load climbs.
The two-speed economy
Canada operates two economies that rarely intersect. One is resource-driven, export-oriented, and responsive to global commodity demand. The other is service-based, local, and built on steady relationships rather than volatile contracts. A boom in the first makes headlines. A slowdown in the second happens quietly, one declined mortgage application at a time.
If you are a service-based business owner, your mortgage readiness depends on optimizing how expenses are claimed, maintaining two years of clean financials, and reducing personal debt before you apply. Lenders value stability documented over 24 months: actual earnings, consistent cash flow, and a track record of paying obligations on time. Copper prices and provincial GDP growth do not change this calculation.




Resource booms concentrate wealth in specific sectors like mining and energy infrastructure while creating economic headwinds for service-based businesses elsewhere in the country. When commodity prices surge, input costs rise, skilled labor migrates to higher-paying regions, and interest rates remain elevated, leaving service business owners facing margin compression and tighter lending standards despite headlines celebrating economic growth. For mortgage qualification, lenders apply fixed underwriting rules based on documented personal income and debt ratios, not provincial GDP figures, meaning a booming resource sector can paradoxically make it harder for self-employed borrowers to access credit.
Resource booms concentrate wealth in narrow corridors. The Northeast has laydown yards where LNG equipment sits before shipment. Open-pit mines in the Interior require haul trucks for servicing. The money flows to heavy equipment operators, engineering firms with energy contracts, and suppliers who move bulk materials. It does not flow to the electrician rewiring a heritage home on Vancouver Island or the bookkeeper running a service practice out of a strip mall.
The confusion comes from treating GDP growth as a single lever that lifts all boats. GDP measures the total value of goods and services produced across the country. When copper prices surge and British Columbia's mining output climbs, the provincial balance sheet improves. Tax revenue rises. Employment in resource extraction ticks up. But a mortgage lender does not underwrite your application based on provincial GDP. They underwrite it based on two years of your T1 Generals, your debt service ratios, and whether your business income meets CMHC's requirement for 24 consecutive months of financial statements.
Why lenders tighten during booms
When resource sectors heat up, banks recalibrate their risk appetite. A portfolio heavy in energy and mining loans creates concentration risk. To balance the exposure, institutions often pull back on complex, manual underwriting, the kind required for self-employed borrowers whose income fluctuates or whose write-offs make qualifying income hard to calculate.
At the same time, a strong economy delays interest rate cuts. The Bank of Canada's overnight rate fell from 4.25 percent in early September 2024 to 3.00 percent by January 2025, as inflation made progress toward the 2% target. Strong export numbers and rising commodity prices kept the central bank cautious. For a contractor hoping lower rates would make the mortgage payment manageable, the resource boom became the obstacle, not the opportunity.
The inflation nobody talks about
Resource booms drive up input costs. Diesel climbs. Lumber becomes expensive because mills prioritize high-margin export orders. Skilled labor migrates toward the Peace River region or the Interior, where day rates are higher. A service business in the Comox Valley sees its material and labor costs rise without seeing a corresponding increase in revenue.
The result is margin compression. Your gross revenue might hold steady, but net income, the number lenders actually use, shrinks. When you file your next tax return, the qualifying income drops. The mortgage you could have qualified for a year ago is now out of reach, even though the headlines say the economy is booming.
What lenders actually see
OSFI's B-20 stress test requires that you qualify at the greater of your contract rate plus 100 basis points, or 5.25 percent. That floor does not move when commodity prices rise. CMHC's 15 percent gross-up for self-employed income allows a small deduction to account for business write-offs, and has not changed in years. The Gross Debt Service ratio ceiling is still 39 percent. The Total Debt Service ceiling is still 44 percent.
These are fixed rules. They do not loosen because Canada's resource exports increased. They tighten when your documented income falls or when your debt load climbs.
The two-speed economy
Canada operates two economies that rarely intersect. One is resource-driven, export-oriented, and responsive to global commodity demand. The other is service-based, local, and built on steady relationships rather than volatile contracts. A boom in the first makes headlines. A slowdown in the second happens quietly, one declined mortgage application at a time.
If you are a service-based business owner, your mortgage readiness depends on optimizing how expenses are claimed, maintaining two years of clean financials, and reducing personal debt before you apply. Lenders value stability documented over 24 months: actual earnings, consistent cash flow, and a track record of paying obligations on time. Copper prices and provincial GDP growth do not change this calculation.
Sources
Read Next
Before the October Bank of Canada Decision: 5 Questions to Ask Your Lender
Extend, Adjust or Let It Lapse: Weighing Canada's Foreign Buyer Ban Before Year End
From 6.4% to 6.5%: How a Small Shift Affects Self-Employed Mortgage Approvals
What BC's Wills Variation Law Means When Disinherited Siblings Threaten Court