How Oil Price Swings Move Your Fixed Mortgage Rate Through the Bond Market
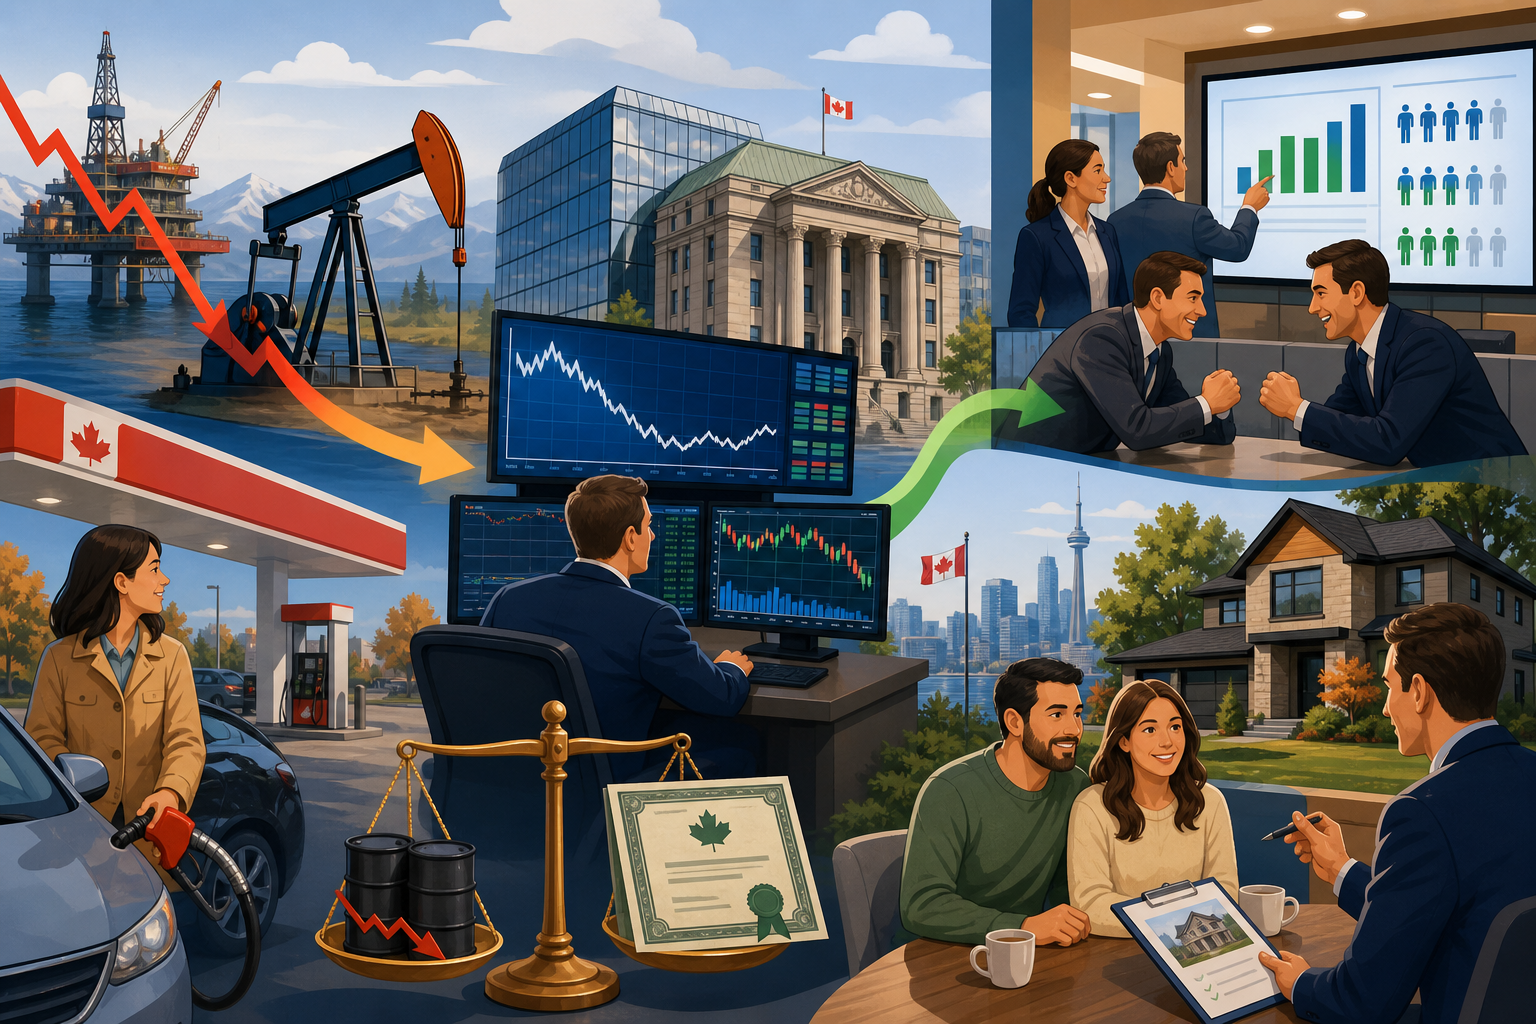
The relationship between oil prices and Canadian mortgage rates runs through the bond market, and September 2026 offers a clear illustration. When global crude prices move sharply, bond yields typically follow within days, and lenders adjust their five-year fixed rates accordingly.
Most people treat oil and mortgage rates as unrelated. One is energy, the other is housing finance. The link is structural, and it runs through the bond market.
The commodity-currency mechanism
Canada exports oil. When global crude prices fall, the economic outlook for Canada softens in the eyes of international investors. Growth projections tick down. Inflation expectations ease because energy is a primary component of the Consumer Price Index, lower fuel costs pull headline inflation lower, which gives the Bank of Canada room to hold or cut rates without overheating the economy.
Bond investors respond by buying Government of Canada bonds, treating them as a safer bet in a cooling environment. When demand for bonds rises, yields fall. That yield, the five-year in particular, is the wholesale cost of money for banks funding five-year fixed mortgages. When it drops, lenders can offer lower rates and still maintain their margin.
The move happens fast. A 10% drop in WTI crude typically shows up in Canadian bond yields within five to ten business days, and when conditions align, lenders adjust their rates within 48 to 72 hours of a yield shift.
Why fixed rates move independently of the Bank of Canada
Variable mortgage rates are tied to the Bank of Canada's overnight rate, which moves only on scheduled announcement dates. Fixed rates are tied to the bond market, which moves every day based on what investors worldwide think will happen to growth, inflation, and currency stability over the next five years.
This is why your neighbour's variable rate can sit unchanged for months while your broker calls to say fixed rates just dropped. The two products are priced off entirely different benchmarks, reacting to different signals.
The bond market is forward-looking. It doesn't care where the economy is today. It cares where inflation and growth will be in 2031. When oil falls and the outlook shifts, bond yields adjust immediately. Lenders update their "special offer" fixed rates within days to stay competitive, often faster than they update the posted rates you see on their websites.
The timing window and the discretionary rate advantage
The posted five-year fixed rate at a major bank might stay frozen for a week while the bond market is already repricing. The "discretionary" or negotiated rate, the one your broker can access or the rate available if you walk into a branch and ask, adjusts faster, sometimes within 48 hours of a yield drop.
That creates a tactical window. If oil drops sharply and you're renewing in the next 60 days, the best time to lock is in the narrow span after yields have fallen but before banks recalibrate their pricing if the market reverses. When these conditions align, lenders typically respond with rate adjustments in the 10-to-20 basis point range before stabilizing.
The counterforce: credit spreads in uncertain conditions
The mechanism has a limit. If oil prices crash so hard that the Canadian dollar weakens dramatically, imports become more expensive. That can actually be inflationary, forcing the Bank of Canada to hold rates higher than the bond yield alone would suggest.
Banks also adjust for risk. If a falling oil price signals recession risk, lenders might widen their credit spread, the margin they charge on top of the bond yield, to cover the potential for defaults. A 15-basis-point drop in the bond yield might turn into only a 10-basis-point drop in the actual rate you're offered, because the bank's margin expanded.
The relationship between oil and rates is a correlation, not a law of physics. But when the stars align, lower oil, falling yields, stable credit conditions, the result is a measurable drop in what you'll pay to borrow for five years. Recognizing these windows when they appear gives borrowers a tactical advantage.




The relationship between oil prices and Canadian mortgage rates runs through the bond market, and September 2026 offers a clear illustration. When global crude prices move sharply, bond yields typically follow within days, and lenders adjust their five-year fixed rates accordingly.
Most people treat oil and mortgage rates as unrelated. One is energy, the other is housing finance. The link is structural, and it runs through the bond market.
The commodity-currency mechanism
Canada exports oil. When global crude prices fall, the economic outlook for Canada softens in the eyes of international investors. Growth projections tick down. Inflation expectations ease because energy is a primary component of the Consumer Price Index, lower fuel costs pull headline inflation lower, which gives the Bank of Canada room to hold or cut rates without overheating the economy.
Bond investors respond by buying Government of Canada bonds, treating them as a safer bet in a cooling environment. When demand for bonds rises, yields fall. That yield, the five-year in particular, is the wholesale cost of money for banks funding five-year fixed mortgages. When it drops, lenders can offer lower rates and still maintain their margin.
The move happens fast. A 10% drop in WTI crude typically shows up in Canadian bond yields within five to ten business days, and when conditions align, lenders adjust their rates within 48 to 72 hours of a yield shift.
Why fixed rates move independently of the Bank of Canada
Variable mortgage rates are tied to the Bank of Canada's overnight rate, which moves only on scheduled announcement dates. Fixed rates are tied to the bond market, which moves every day based on what investors worldwide think will happen to growth, inflation, and currency stability over the next five years.
This is why your neighbour's variable rate can sit unchanged for months while your broker calls to say fixed rates just dropped. The two products are priced off entirely different benchmarks, reacting to different signals.
The bond market is forward-looking. It doesn't care where the economy is today. It cares where inflation and growth will be in 2031. When oil falls and the outlook shifts, bond yields adjust immediately. Lenders update their "special offer" fixed rates within days to stay competitive, often faster than they update the posted rates you see on their websites.
The timing window and the discretionary rate advantage
The posted five-year fixed rate at a major bank might stay frozen for a week while the bond market is already repricing. The "discretionary" or negotiated rate, the one your broker can access or the rate available if you walk into a branch and ask, adjusts faster, sometimes within 48 hours of a yield drop.
That creates a tactical window. If oil drops sharply and you're renewing in the next 60 days, the best time to lock is in the narrow span after yields have fallen but before banks recalibrate their pricing if the market reverses. When these conditions align, lenders typically respond with rate adjustments in the 10-to-20 basis point range before stabilizing.
The counterforce: credit spreads in uncertain conditions
The mechanism has a limit. If oil prices crash so hard that the Canadian dollar weakens dramatically, imports become more expensive. That can actually be inflationary, forcing the Bank of Canada to hold rates higher than the bond yield alone would suggest.
Banks also adjust for risk. If a falling oil price signals recession risk, lenders might widen their credit spread, the margin they charge on top of the bond yield, to cover the potential for defaults. A 15-basis-point drop in the bond yield might turn into only a 10-basis-point drop in the actual rate you're offered, because the bank's margin expanded.
The relationship between oil and rates is a correlation, not a law of physics. But when the stars align, lower oil, falling yields, stable credit conditions, the result is a measurable drop in what you'll pay to borrow for five years. Recognizing these windows when they appear gives borrowers a tactical advantage.
Sources
Read Next
Before the October Bank of Canada Decision: 5 Questions to Ask Your Lender
Extend, Adjust or Let It Lapse: Weighing Canada's Foreign Buyer Ban Before Year End
From 6.4% to 6.5%: How a Small Shift Affects Self-Employed Mortgage Approvals
What BC's Wills Variation Law Means When Disinherited Siblings Threaten Court