How BC Contractors Present Income to Qualify for a Mortgage in 2026
A drywaller in Nanaimo can gross $140,000 but show $62,000 on Line 15000 of her Notice of Assessment after writing off truck payments, tools, and a home office. A lender looking at that NOA sees $62,000. A lender looking at her business bank statements and her CRA filing together can sometimes see more.
The gap between what you earn and what shows up on your tax return is the central problem self-employed buyers face. There are two paths through it.
The Traditional Route: Line 15000 and the Two-Year Average
Most A-lenders in BC will average your Line 15000 (Total Income) from two consecutive years of Notices of Assessment. If 2024 shows $58,000 and 2025 shows $66,000, they use $62,000. Add back the 15% CMHC gross-up and you're qualifying on roughly $71,300.
The two-year requirement is firm. CMHC updated their self-employed program in August 2026 to require 24 consecutive months of financials for high-ratio mortgages. If you incorporated in late 2024, you need full tax years for both 2024 and 2025. One year filed plus six months of statements won't get you there with most insurers.
You must be current on all filings. A Notice of Assessment showing a balance owing to CRA is a barrier. Lenders treat tax debt as a super-priority lien. If you owe $8,000 in back taxes, pay it before you apply.
For incorporated contractors, some lenders will consider both your T4 salary and retained earnings in the corporation, provided the business has strong financials. This works best when you've left profits in the company intentionally rather than distributing them as dividends.
The Stated Income Path: When Your Bank Statements Tell a Better Story
The Self-Employed (Stated Income) program looks at gross business revenue minus essential expenses. A painter who deposits $11,000 per month and spends $3,500 on materials, fuel, and insurance can show $7,500 monthly net. Annualized, that's $90,000, which may be $20,000 higher than what appears on Line 15000 after depreciation and other tax deductions.
This route requires more documentation: 24 months of business bank statements, copies of invoices, proof of a valid business license, and often a letter from your accountant explaining the difference between taxable income and cash flow.
The trade-off is down payment. Traditional programs start at 5% down for the first $500,000 of the purchase price. Stated Income products from Sagen or Canada Guaranty typically require 10% to 20% down depending on the file.
Lenders also apply a "reasonableness test." If you're an HVAC tech claiming $180,000 net and the BC industry average for your trade is $75,000, expect follow-up questions. They'll compare your stated income to industry benchmarks and may request client contracts or proof of specialized certifications.
What to Gather Before You Talk to an Advisor
Bring two years of Notices of Assessment, two years of T1 Generals, and 24 months of business bank statements. If you're incorporated, add two years of corporate tax returns (T2s) and your most recent balance sheet.
Check that your GST remittances are current. Being behind on GST is a red flag. Lenders see CRA as first in line.
If your down payment is coming from your corporation, it must be documented as either a dividend or a shareholder loan. Both have tax implications. Coordinate with your accountant before you move the money.
Seasonal income, common in forestry, tourism, or landscaping trades in the Comox Valley, requires a longer look-back. Lenders want to see the pattern repeat across two full cycles.
A credit score of 680 or higher opens the best rates. Below that, you're into B-lender territory, which usually means a 1% lender fee and a rate premium of 1 to 3 percentage points.
The path forward is clearer when the paperwork is organized and your advisor knows what they're looking at. The income is there. The question is how to show it in a way the lender can use.



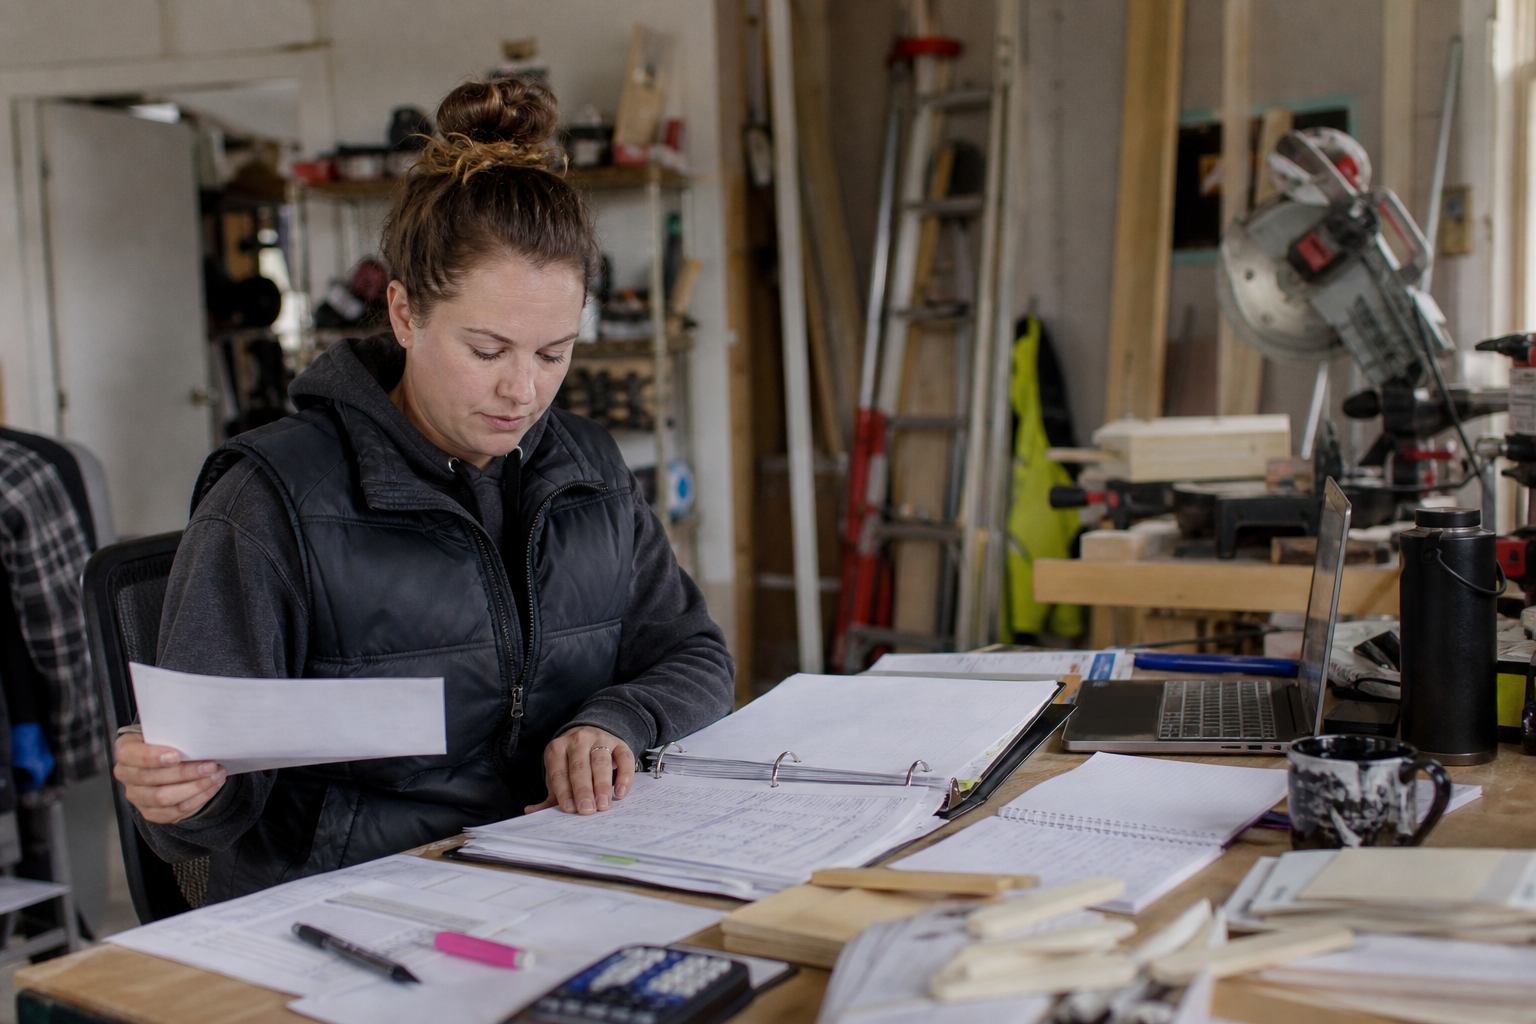

A drywaller in Nanaimo can gross $140,000 but show $62,000 on Line 15000 of her Notice of Assessment after writing off truck payments, tools, and a home office. A lender looking at that NOA sees $62,000. A lender looking at her business bank statements and her CRA filing together can sometimes see more.
The gap between what you earn and what shows up on your tax return is the central problem self-employed buyers face. There are two paths through it.
The Traditional Route: Line 15000 and the Two-Year Average
Most A-lenders in BC will average your Line 15000 (Total Income) from two consecutive years of Notices of Assessment. If 2024 shows $58,000 and 2025 shows $66,000, they use $62,000. Add back the 15% CMHC gross-up and you're qualifying on roughly $71,300.
The two-year requirement is firm. CMHC updated their self-employed program in August 2026 to require 24 consecutive months of financials for high-ratio mortgages. If you incorporated in late 2024, you need full tax years for both 2024 and 2025. One year filed plus six months of statements won't get you there with most insurers.
You must be current on all filings. A Notice of Assessment showing a balance owing to CRA is a barrier. Lenders treat tax debt as a super-priority lien. If you owe $8,000 in back taxes, pay it before you apply.
For incorporated contractors, some lenders will consider both your T4 salary and retained earnings in the corporation, provided the business has strong financials. This works best when you've left profits in the company intentionally rather than distributing them as dividends.
The Stated Income Path: When Your Bank Statements Tell a Better Story
The Self-Employed (Stated Income) program looks at gross business revenue minus essential expenses. A painter who deposits $11,000 per month and spends $3,500 on materials, fuel, and insurance can show $7,500 monthly net. Annualized, that's $90,000, which may be $20,000 higher than what appears on Line 15000 after depreciation and other tax deductions.
This route requires more documentation: 24 months of business bank statements, copies of invoices, proof of a valid business license, and often a letter from your accountant explaining the difference between taxable income and cash flow.
The trade-off is down payment. Traditional programs start at 5% down for the first $500,000 of the purchase price. Stated Income products from Sagen or Canada Guaranty typically require 10% to 20% down depending on the file.
Lenders also apply a "reasonableness test." If you're an HVAC tech claiming $180,000 net and the BC industry average for your trade is $75,000, expect follow-up questions. They'll compare your stated income to industry benchmarks and may request client contracts or proof of specialized certifications.
What to Gather Before You Talk to an Advisor
Bring two years of Notices of Assessment, two years of T1 Generals, and 24 months of business bank statements. If you're incorporated, add two years of corporate tax returns (T2s) and your most recent balance sheet.
Check that your GST remittances are current. Being behind on GST is a red flag. Lenders see CRA as first in line.
If your down payment is coming from your corporation, it must be documented as either a dividend or a shareholder loan. Both have tax implications. Coordinate with your accountant before you move the money.
Seasonal income, common in forestry, tourism, or landscaping trades in the Comox Valley, requires a longer look-back. Lenders want to see the pattern repeat across two full cycles.
A credit score of 680 or higher opens the best rates. Below that, you're into B-lender territory, which usually means a 1% lender fee and a rate premium of 1 to 3 percentage points.
The path forward is clearer when the paperwork is organized and your advisor knows what they're looking at. The income is there. The question is how to show it in a way the lender can use.
Sources
Read Next
Before the October Bank of Canada Decision: 5 Questions to Ask Your Lender
Extend, Adjust or Let It Lapse: Weighing Canada's Foreign Buyer Ban Before Year End
From 6.4% to 6.5%: How a Small Shift Affects Self-Employed Mortgage Approvals
What BC's Wills Variation Law Means When Disinherited Siblings Threaten Court