Before You Put Surplus Cash into the Market: 4 Steps to Maximize Your Real Estate Borrowing Power
You have surplus cash sitting in your corporate account, and the market chatter is getting loud. It is tempting to feel like that money should be chasing the next run. But if you plan to buy real estate soon, parking capital in volatile assets ties up money you cannot control and leaves your debt ratios bloated right when underwriters start reviewing your files.
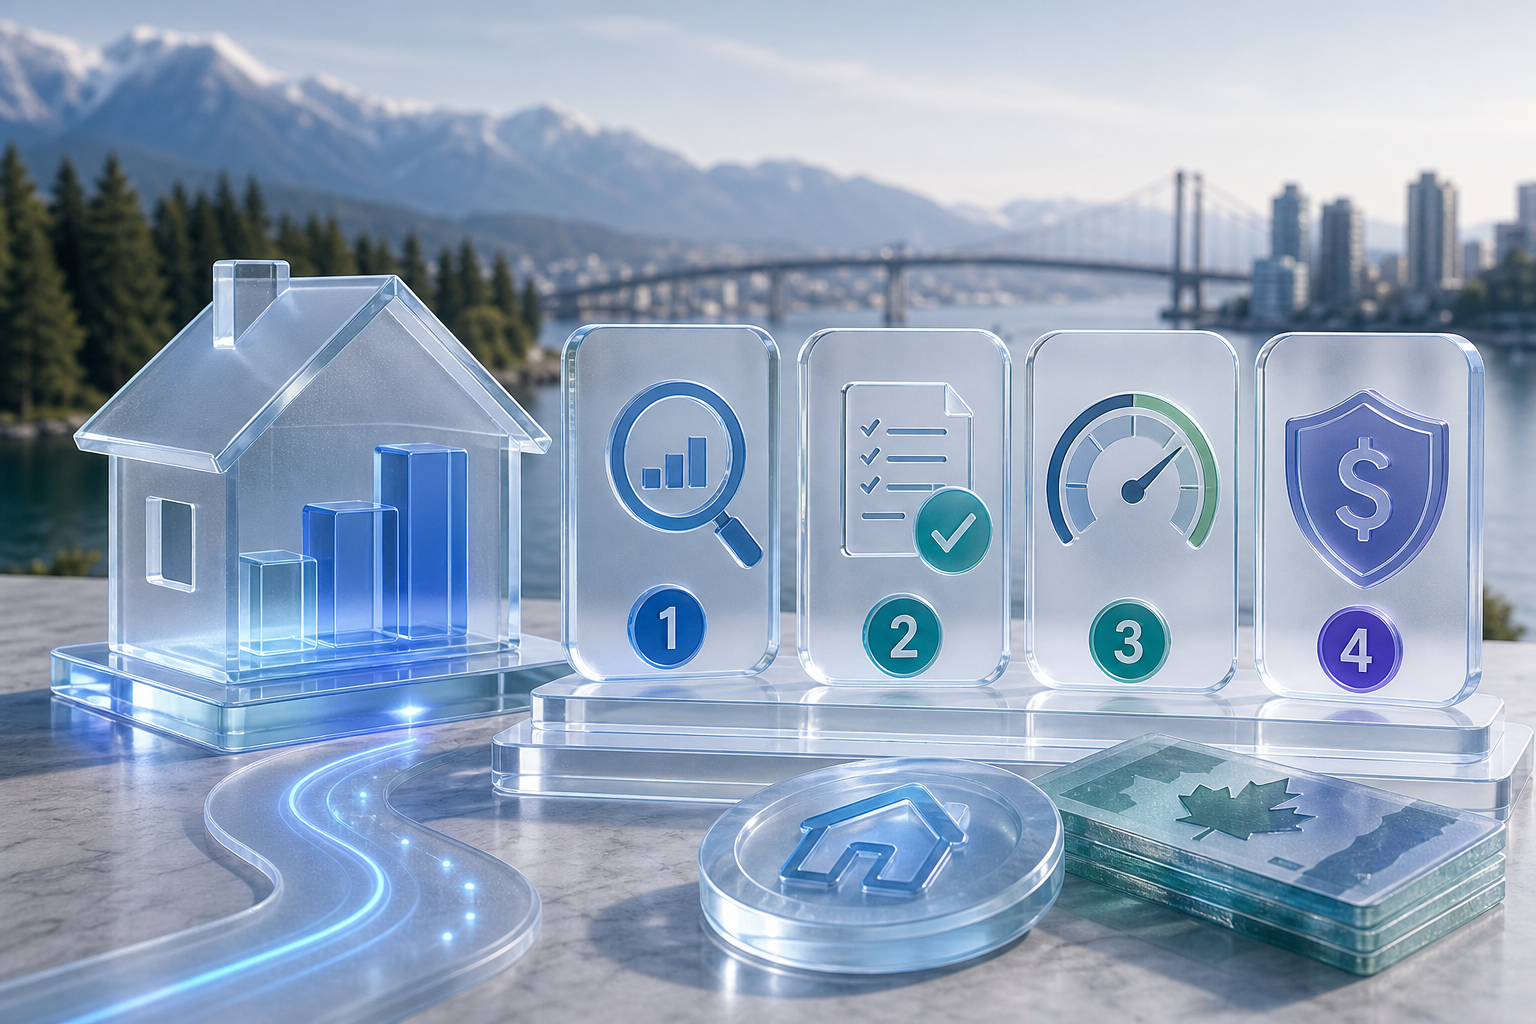
Here is what I call the Balance Sheet Yield Strategy. It is four practical steps to turn corporate cash into clean borrowing equity, in order.
1. Audit the corporate debts that pinch your ratios
Pull your corporate balance sheet and list every liability. Focus on the ones with recurring monthly payments that bite hardest into your debt-service ratios.
Underwriters look closely at these monthly obligations. Even a modest balance on a corporate credit line can cut deeply into the borrowing room a lender will approve for your next property.
2. Direct retained earnings toward high-cost balances
Take your surplus cash and wipe out those high-cost credit lines instead of hunting for paper gains.
Paying off corporate debt is not a defensive retreat. It provides a guaranteed after-tax return while removing monthly drag, leaving you with the clean cash flow that mortgage underwriters love to see.
3. Establish an offset or revolving credit facility
Set up an offset structure or a flexible revolving facility behind the scenes.
You never want to starve your business of working capital. This structure preserves your day-to-day operational liquidity, keeping funds accessible whenever you need them while keeping your balance sheet lean.
4. Model your expanded borrowing capacity with an advisor
Run your updated corporate balance sheet through standard lending calculations before you look at properties.
Clearing corporate liabilities expands your buying power in a direct, predictable way. Knowing your exact numbers in advance ensures you only look at deals you know you can finance.
Once you have checked all four
Take your modeled numbers to market. With lower debt ratios, preserved cash flow, and steady liquidity behind you, you can make your next property offer with complete confidence.

You have surplus cash sitting in your corporate account, and the market chatter is getting loud. It is tempting to feel like that money should be chasing the next run. But if you plan to buy real estate soon, parking capital in volatile assets ties up money you cannot control and leaves your debt ratios bloated right when underwriters start reviewing your files.
Here is what I call the Balance Sheet Yield Strategy. It is four practical steps to turn corporate cash into clean borrowing equity, in order.
1. Audit the corporate debts that pinch your ratios
Pull your corporate balance sheet and list every liability. Focus on the ones with recurring monthly payments that bite hardest into your debt-service ratios.
Underwriters look closely at these monthly obligations. Even a modest balance on a corporate credit line can cut deeply into the borrowing room a lender will approve for your next property.
2. Direct retained earnings toward high-cost balances
Take your surplus cash and wipe out those high-cost credit lines instead of hunting for paper gains.
Paying off corporate debt is not a defensive retreat. It provides a guaranteed after-tax return while removing monthly drag, leaving you with the clean cash flow that mortgage underwriters love to see.
3. Establish an offset or revolving credit facility
Set up an offset structure or a flexible revolving facility behind the scenes.
You never want to starve your business of working capital. This structure preserves your day-to-day operational liquidity, keeping funds accessible whenever you need them while keeping your balance sheet lean.
4. Model your expanded borrowing capacity with an advisor
Run your updated corporate balance sheet through standard lending calculations before you look at properties.
Clearing corporate liabilities expands your buying power in a direct, predictable way. Knowing your exact numbers in advance ensures you only look at deals you know you can finance.
Once you have checked all four
Take your modeled numbers to market. With lower debt ratios, preserved cash flow, and steady liquidity behind you, you can make your next property offer with complete confidence.
Read Next
Keep Business Debt on Your Personal File or Move It to the Corporation? Here is Who Each One Is For
Take CPP at 65 or Wait Until 70? Here's Who Each One Is For
The Shifting Rate Isn't the Story. Your 120-Day Window Is.
How to Calculate Your Real Borrowing Ceiling Before You Write an Offer