28% of Working Canadians Live Paycheque to Paycheque: Five Habits That Keep You Trapped
The coffee shop owner in downtown Courtenay brings in $110,000 a year but manages cash flow carefully, waiting for Friday's deposit to clear before paying Thursday's suppliers. The electrician two blocks over clears six figures and carries a $22,000 Visa balance at 19.9%. Both are managing real constraints that five specific behaviours can help address.
You're paying minimum-plus-twenty instead of attacking the balance
Most people who call minimum payments "progress" are actually standing still. A $15,000 credit card balance at 19.9% costs you $249 a month in interest alone. Pay $300 and you've moved $51 toward freedom. It takes 12 years to clear. Pay $600 and you're done in 31 months. The trap isn't the debt. It's the monthly muscle memory of paying what feels manageable instead of what moves the needle.
Debt consolidation through a line of credit isn't about total debt, it's about lowering the monthly bleed. A $30,000 balance at 6.5% instead of 19.9% frees up $337 a month. That's the difference between living on Tuesday's invoice and having a buffer.
Your "needs" bucket includes wants you've forgotten about
The 50/30/20 rule says 50% of income covers needs. In Courtenay and across Vancouver Island, rent alone can hit 35% before utilities, groceries or fuel. The real problem is the eight subscriptions you forgot you're paying.
Go through three months of bank statements and highlight every recurring charge. Spotify, Netflix, the gym membership you haven't used since March, the meal kit that auto-renews, the cloud storage upgrade you signed up for in 2023. Individually they're $12 or $18. Together they're $240 a month, nearly $3,000 a year, leaving your account before you see your paycheque.
You're not tracking mileage, and it's costing you thousands
Contractors and tradespeople in BC routinely drive 10,000 to 15,000 business kilometres a year and claim zero. The CRA mileage rate for 2026 is 73 cents per kilometre for the first 5,000 business kilometres, then 67 cents per kilometre thereafter. At 12,000 kilometres, that's $8,340 in deductions you're leaving on the table. If you're in the 30% marginal bracket, you just donated $2,502 in unclaimed deductions.
MileIQ and Stride track automatically using GPS. Set it once in January. The app does the rest. Come tax time, you have a log the CRA accepts without a notebook or guesswork.
Your RRSP contributions are mistimed
Contributing to an RRSP in February to claim last year's deduction makes sense for the refund. But if you're paycheque to paycheque, that refund arrives in May, months after you needed it. The better move for contractors with variable income: make your RRSP contributions in your highest-earning months, claim the deduction immediately through Form T1213, and reduce your withholding tax right away. You get the cash flow benefit when you actually have money to contribute, not six months later when you're already behind.
You haven't built the one-month bridge
Breaking the paycheque cycle doesn't start with wealth building. It starts with a single, boring goal: one month of fixed costs in a separate account. Not six months. One.
Calculate rent, utilities, minimum debt payments, groceries and fuel. If that's $3,800, your target is $3,800. When next month's bills hit, you pay them from the bridge account and refill it from this month's income. You've just stopped paying last month's life with next week's invoice.
For the Courtenay contractor, this usually takes 6 to 9 months of small monthly deposits, $200, $400, whatever the job allowed. It's not fast. But the first time you pay your Hydro bill without checking your balance first, the entire strategy clicks.
The traps aren't complicated, and neither are the exits.



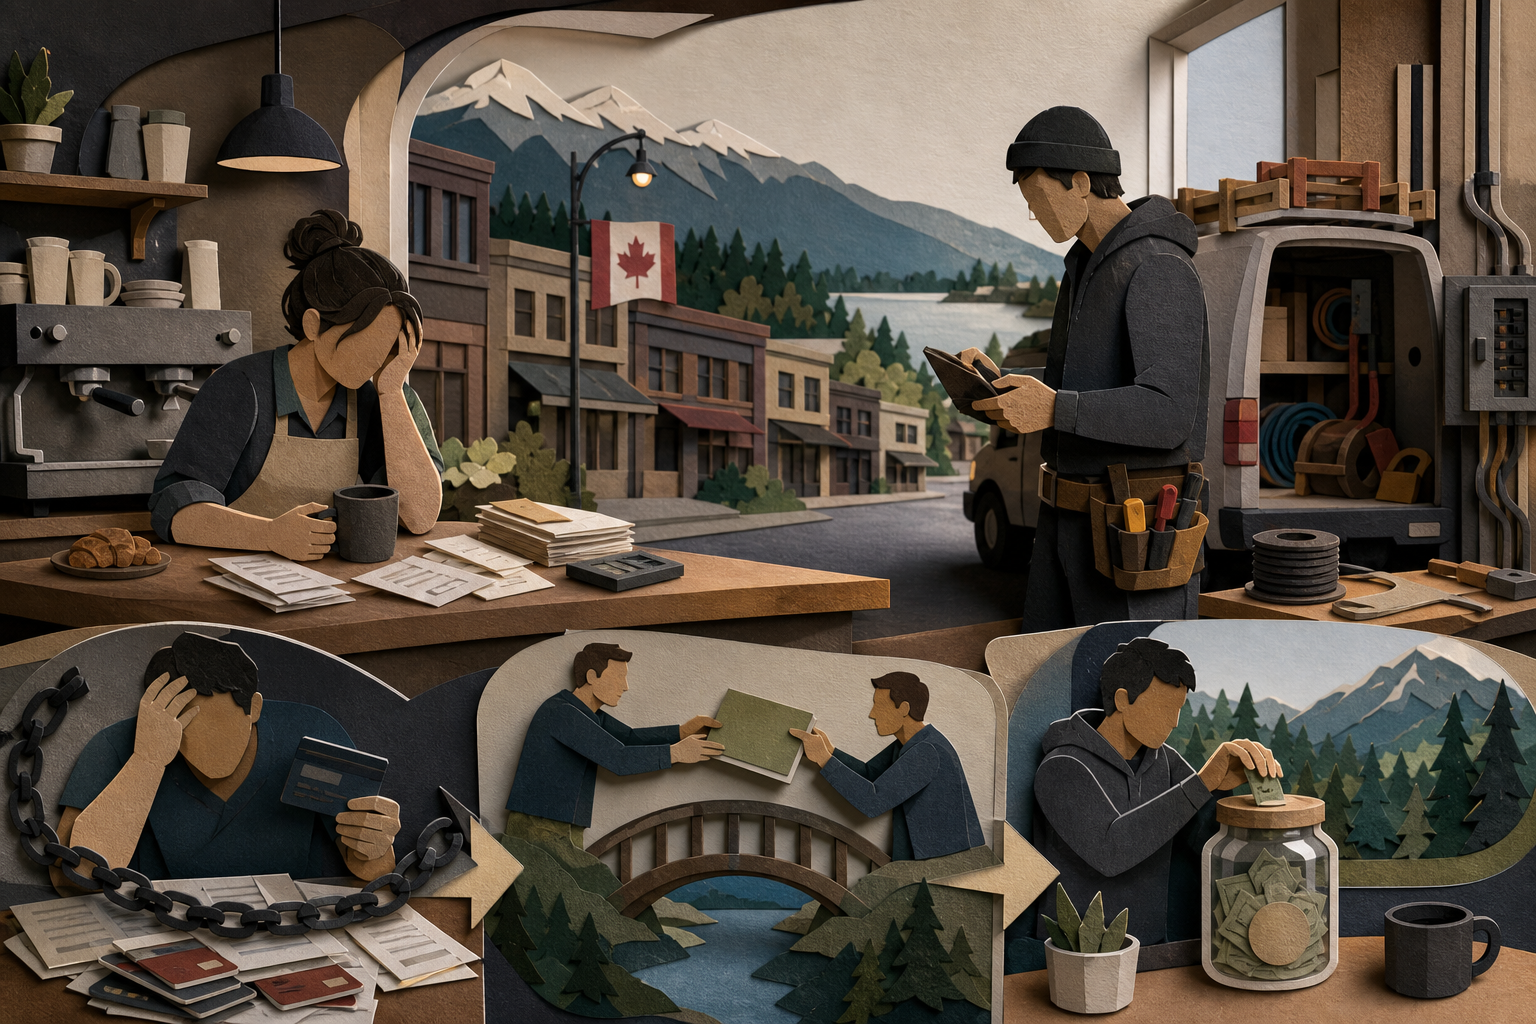

The coffee shop owner in downtown Courtenay brings in $110,000 a year but manages cash flow carefully, waiting for Friday's deposit to clear before paying Thursday's suppliers. The electrician two blocks over clears six figures and carries a $22,000 Visa balance at 19.9%. Both are managing real constraints that five specific behaviours can help address.
You're paying minimum-plus-twenty instead of attacking the balance
Most people who call minimum payments "progress" are actually standing still. A $15,000 credit card balance at 19.9% costs you $249 a month in interest alone. Pay $300 and you've moved $51 toward freedom. It takes 12 years to clear. Pay $600 and you're done in 31 months. The trap isn't the debt. It's the monthly muscle memory of paying what feels manageable instead of what moves the needle.
Debt consolidation through a line of credit isn't about total debt, it's about lowering the monthly bleed. A $30,000 balance at 6.5% instead of 19.9% frees up $337 a month. That's the difference between living on Tuesday's invoice and having a buffer.
Your "needs" bucket includes wants you've forgotten about
The 50/30/20 rule says 50% of income covers needs. In Courtenay and across Vancouver Island, rent alone can hit 35% before utilities, groceries or fuel. The real problem is the eight subscriptions you forgot you're paying.
Go through three months of bank statements and highlight every recurring charge. Spotify, Netflix, the gym membership you haven't used since March, the meal kit that auto-renews, the cloud storage upgrade you signed up for in 2023. Individually they're $12 or $18. Together they're $240 a month, nearly $3,000 a year, leaving your account before you see your paycheque.
You're not tracking mileage, and it's costing you thousands
Contractors and tradespeople in BC routinely drive 10,000 to 15,000 business kilometres a year and claim zero. The CRA mileage rate for 2026 is 73 cents per kilometre for the first 5,000 business kilometres, then 67 cents per kilometre thereafter. At 12,000 kilometres, that's $8,340 in deductions you're leaving on the table. If you're in the 30% marginal bracket, you just donated $2,502 in unclaimed deductions.
MileIQ and Stride track automatically using GPS. Set it once in January. The app does the rest. Come tax time, you have a log the CRA accepts without a notebook or guesswork.
Your RRSP contributions are mistimed
Contributing to an RRSP in February to claim last year's deduction makes sense for the refund. But if you're paycheque to paycheque, that refund arrives in May, months after you needed it. The better move for contractors with variable income: make your RRSP contributions in your highest-earning months, claim the deduction immediately through Form T1213, and reduce your withholding tax right away. You get the cash flow benefit when you actually have money to contribute, not six months later when you're already behind.
You haven't built the one-month bridge
Breaking the paycheque cycle doesn't start with wealth building. It starts with a single, boring goal: one month of fixed costs in a separate account. Not six months. One.
Calculate rent, utilities, minimum debt payments, groceries and fuel. If that's $3,800, your target is $3,800. When next month's bills hit, you pay them from the bridge account and refill it from this month's income. You've just stopped paying last month's life with next week's invoice.
For the Courtenay contractor, this usually takes 6 to 9 months of small monthly deposits, $200, $400, whatever the job allowed. It's not fast. But the first time you pay your Hydro bill without checking your balance first, the entire strategy clicks.
The traps aren't complicated, and neither are the exits.
Sources
Read Next
Before the October Bank of Canada Decision: 5 Questions to Ask Your Lender
Extend, Adjust or Let It Lapse: Weighing Canada's Foreign Buyer Ban Before Year End
From 6.4% to 6.5%: How a Small Shift Affects Self-Employed Mortgage Approvals
What BC's Wills Variation Law Means When Disinherited Siblings Threaten Court